Bank of Montreal
Market Linked Securities
Filed Pursuant to Rule 433
Registration Statement No. 333-285508
|
Bank of Montreal Market Linked Securities |
|
|
Market Linked Securities—Callable with Contingent Coupon with Daily Observation and Contingent Downside Principal at Risk Securities Linked to the Lowest Performing of the Nasdaq-100 Index®, the Russell 2000® Index and the S&P 500® Index due April 27, 2029 Term Sheet to Preliminary Pricing Supplement dated October 1, 2026 |
Summary of Terms
| Issuer: | Bank of Montreal |
| Market Measures: | The Nasdaq-100 Index®, the Russell 2000® Index and the S&P 500® Index (each referred to as an “Underlier,” and collectively as the “Underliers”) |
| Pricing Date*: | October 30, 2026 |
| Issue Date*: | November 4, 2026 |
| Face Amount and Original Offering Price: |
$1,000 per security |
| Contingent Coupon Payments: |
On each contingent coupon payment date, unless the securities have been previously redeemed, you will receive a contingent coupon payment at a per annum rate equal to the contingent coupon rate if the closing value of the lowest performing Underlier on each eligible trading day during the related observation period is greater than or equal to its coupon threshold value. Each “contingent coupon payment,” if any, will be calculated per security as follows: ($1,000 × contingent coupon rate)/4 |
| Contingent Coupon Payment Dates: |
Quarterly, on the third business day following each observation period end-date; provided that the contingent coupon payment date with respect to the final observation period will be the stated maturity date |
| Contingent Coupon Rate: | At least 9.00% per annum, to be determined on the pricing date |
| Observation Periods: | Each observation period will consist of each day that is a trading day for at least one Underlier (each such day, an “eligible trading day”) from but excluding an observation period end-date to and including the following observation period end-date, provided that the first observation period will consist of each eligible trading day from but excluding the pricing date to and including the first observation period end-date |
| Observation Period End- Dates*: |
Quarterly, on the 24th day of each January, April, July and October, commencing January 2027 and ending January 2029, and April 24, 2029 (the “final calculation day”) |
| Optional Redemption: | Bank of Montreal may, at its option, redeem the securities, in whole but not in part, on any optional redemption date. If Bank of Montreal elects to redeem the securities prior to stated maturity, you will be entitled to receive on the applicable optional redemption date a cash payment per security in U.S. dollars equal to the face amount plus a final contingent coupon payment, if otherwise payable |
| Optional Redemption Dates: |
Quarterly, beginning approximately three months after the issue date, on the contingent coupon payment dates following each observation period end-date scheduled to occur from January 2027 to January 2029, inclusive |
| Maturity Payment Amount (per security): |
If Bank of Montreal does not redeem the securities prior to the stated maturity date: · if the ending value of the lowest performing Underlier on the final calculation day is greater than or equal to its downside threshold value: $1,000; or · if the ending value of the lowest performing Underlier on the final calculation day is less than its downside threshold value: $1,000 × performance factor of the lowest performing Underlier on the final calculation day |
| Stated Maturity Date*: | April 27, 2029 |
| Lowest Performing Underlier: |
For any eligible trading day during an observation period (including the final calculation day), the “lowest performing Underlier” will be the Underlier with the lowest performance factor on that day |
| Performance Factor: | With respect to an Underlier on any eligible trading day during an observation period, its closing value on such day divided by its starting value (expressed as a percentage) |
| Starting Value: | With respect to each Underlier, its closing value on the pricing date |
| Ending Value: | With respect to each Underlier, its closing value on the final calculation day |
| Coupon Threshold Value: | With respect to each Underlier, 70% of its starting value |
|
*subject to change | |
Summary of Terms (continued)
| Downside Threshold Value: | With respect to each Underlier, 60% of its starting value |
| Calculation Agent: | BMO Capital Markets Corp., an affiliate of the issuer |
| Denominations: | $1,000 and any integral multiple of $1,000 |
| Agent Discount**: | Up to 2.075% for Wells Fargo Securities, LLC (“WFS”). Of that agent discount, Wells Fargo Advisors (“WFA”), may receive a selling concession of up to 1.50% and a distribution expense fee of up to 0.075% |
| CUSIP: | 06376ML28 |
| Material Tax Consequences: | See the preliminary pricing supplement |
** In addition, selected dealers may receive a fee of up to 0.20% for marketing and other services.
Hypothetical Payout Profile (maturity payment amount)
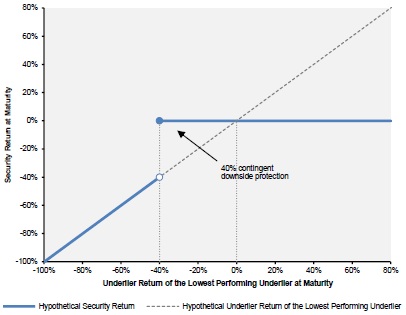
If Bank of Montreal does not redeem the securities prior to stated maturity and the ending value of the lowest performing Underlier on the final calculation day is less than its downside threshold value, you will lose more than 40%, and possibly all, of the face amount of your securities at stated maturity.
Any return on the securities will be limited to the sum of your contingent coupon payments, if any. You will not participate in any appreciation of any Underlier, but you will have full downside exposure to the lowest performing Underlier on the final calculation day if the ending value of that Underlier is less than its downside threshold value.
On the date of the accompanying preliminary pricing supplement, the estimated initial value of the securities is $960.00 per security. The estimated initial value of the securities at pricing may differ from this value but will not be less than $910.00 per security. However, as discussed in more detail in the accompanying preliminary pricing supplement, the actual value of the securities at any time will reflect many factors and cannot be predicted with accuracy. See “Estimated Value of the Securities” in the accompanying preliminary pricing supplement.
Preliminary Pricing Supplement:
https://www.sec.gov/Archives/edgar/data/927971/000121465926012437/g928261424b2.htm
The securities have complex features and investing in the securities involves risks not associated with an investment in conventional debt securities. See “Selected Risk Considerations” in this term sheet and the accompanying preliminary pricing supplement and “Risk Factors” in the accompanying product supplement.
This introductory term sheet does not provide all of the information that an investor should consider prior to making an investment decision.
Investors should carefully review the accompanying preliminary pricing supplement, product supplement, underlying supplement, prospectus supplement and prospectus before making a decision to invest in the securities.
NOT A BANK DEPOSIT AND NOT INSURED OR GUARANTEED BY THE FDIC OR ANY OTHER GOVERNMENTAL AGENCY
Selected Risk Considerations
The risks set forth below are discussed in detail in the “Selected Risk Considerations” section in the accompanying preliminary pricing supplement and the “Risk Factors” section in the accompanying product supplement. Please review those risk disclosures carefully.
Risks Relating To The Securities Generally
| · | If We Do Not Redeem The Securities Prior To Stated Maturity, You May Lose Some Or All Of The Face Amount Of Your Securities At Stated Maturity. |
| · | The Securities Do Not Provide For Fixed Payments Of Interest And You May Receive No Contingent Coupon Payments On One Or More Contingent Coupon Payment Dates, Or Even Throughout The Entire Term Of The Securities. |
| · | Whether You Receive A Contingent Coupon Payment On A Contingent Coupon Payment Date Will Depend On The Closing Value Of The Lowest Performing Underlier On Each Eligible Trading Day During The Related Observation Period. |
| · | The Securities Are Subject To The Full Risks Of Each Underlier And Will Be Negatively Affected If Any Underlier Performs Poorly, Even If The Other Underliers Perform Favorably. |
| · | Your Return On The Securities Will Depend Solely On The Performance Of The Underlier That Is The Lowest Performing Underlier On Each Eligible Trading Day During The Observation Periods, Including The Final Calculation Day, And You Will Not Benefit In Any Way From The Performance Of The Better Performing Underliers. |
| · | You Will Be Subject To Risks Resulting From The Relationship Among The Underliers. |
| · | You May Be Fully Exposed To The Decline In The Lowest Performing Underlier On The Final Calculation Day From Its Starting Value, But Will Not Participate In Any Positive Performance Of Any Underlier. |
| · | Higher Contingent Coupon Rates Are Associated With Greater Risk. |
| · | Our Redemption Right May Limit Your Potential To Receive Contingent Coupon Payments. |
| · | The Securities Are Subject To Credit Risk. |
| · | The U.S. Federal Income Tax Consequences Of An Investment In The Securities Are Unclear. |
| · | The Stated Maturity Date May Be Postponed If The Final Calculation Day Is Postponed. |
Risks Relating To The Estimated Value Of The Securities And Any Secondary Market
| · | The Estimated Value Of The Securities On The Pricing Date, Based On Our Proprietary Pricing Models, Will Be Less Than The Original Offering Price. |
| · | The Terms Of The Securities Are Not Determined By Reference To The Credit Spreads For Our Conventional Fixed-Rate Debt. |
| · | The Estimated Value Of The Securities Is Not An Indication Of The Price, If Any, At Which WFS Or Any Other Person May Be Willing To Buy The Securities From You In The Secondary Market. |
| · | The Value Of The Securities Prior To Stated Maturity Will Be Affected By Numerous Factors, Some Of Which Are Related In Complex Ways. |
| · | The Securities Will Not Be Listed On Any Securities Exchange And We Do Not Expect A Trading Market For The Securities To Develop. |
Risks Relating To The Underliers
| · | Any Payments On The Securities Will Depend Upon The Performance Of The Underliers And Therefore The Securities Are Subject To The Following Risks, Each As Discussed In More Detail In The Accompanying Product Supplement. |
| o | Investing In The Securities Is Not The Same As Investing In The Underliers. |
| o | Historical Values Of The Underliers Should Not Be Taken As An Indication Of The Future Performance Of The Underliers During The Term Of The Securities. |
| o | Changes That Affect The Underliers May Adversely Affect The Value Of The Securities And Any Payments On The Securities. |
| o | We Cannot Control Actions By Any Of The Unaffiliated Companies Whose Securities Are Included In The Underliers. |
| o | We And Our Affiliates Have No Affiliation With Any Underlier Sponsor And Have Not Independently Verified Their Public Disclosure Of Information. |
| · | The Securities Are Subject To Risks Relating To Non-U.S. Securities With Respect To The Nasdaq-100 Index®. |
| · | The Nasdaq-100 Index® Has Recently Undergone Significant Methodology Changes And, As A Result, The Nasdaq-100 Index® May Perform Differently Than It Would Have Performed Under Its Prior Methodology. |
| · | The Securities Are Subject To Small-Capitalization Companies Risk With Respect To The Russell 2000® Index. |
Risks Relating To Conflicts Of Interest
| · | Our Economic Interests And Those Of Any Dealer Participating In The Offering Are Potentially Adverse To Your Interests. |
The Issuer has filed a registration statement (including a prospectus) with the SEC for the offering to which this document relates. Before you invest, you should read the prospectus in that registration statement and the other documents that the Issuer has filed with the SEC for more complete information about us and this offering. You may obtain these documents free of charge by visiting the SEC’s website at http://www.sec.gov. Alternatively, the Issuer will arrange to send to you the prospectus (as supplemented by the prospectus supplement) if you request it by calling the Issuer’s agent toll-free at 1-877-369-5412.
Wells Fargo Advisors is a trade name used by Wells Fargo Clearing Services, LLC and Wells Fargo Advisors Financial Network, LLC, members SIPC, separate registered broker-dealers and non-bank affiliates of Wells Fargo & Company.
2