 |
Filed Pursuant to Rule 433
Registration Statement No. 333-283969
Dated October 20, 2026
|
|
Market Linked Securities – Auto-Callable with Fixed Coupon and Geared Buffer Downside
Principal at Risk Securities Linked to the common stock of Generac Holdings Inc. due April 28, 2028
Term Sheet to Preliminary Pricing Supplement dated October 20, 2026
|
|
Summary of Terms
|
Issuer:
|
The Toronto-Dominion Bank (the “Bank”)
|
||
|
Underwriters:
|
TD Securities (USA) LLC. and Wells Fargo Securities, LLC
|
||
|
Market Measure:
|
The common stock of Generac Holdings Inc. (the “Underlying Stock”).
|
||
|
Pricing Date*:
|
October 23, 2026
|
||
|
Issue Date*:
|
October 28, 2026
|
||
|
Face Amount and
Original Offering
Price:
|
$1,000 per security
|
||
|
Coupon Payments:
|
On each coupon payment date, unless previously automatically called, you will receive a fixed coupon payment at a per annum rate equal to the coupon rate. Each “coupon payment,” will
be calculated per security as follows: ($1,000 × coupon rate)/4. Each coupon payment will be rounded to the nearest cent, with one-half cent rounded upward.
|
||
|
Coupon Payment
Dates:
|
Quarterly, on the 28th day of each January, April, July, October, commencing in January 2027 and ending on the stated maturity date.
|
||
|
Coupon Rate:
|
At least 12.00% per annum, to be determined on the pricing date
|
||
|
Automatic Call:
|
If the stock closing price of the Underlying Stock on any call date is greater than or equal to the starting price, the securities will be automatically called and, on the related call
settlement date, you will be entitled to receive a cash payment per security in U.S. dollars equal to the face amount plus the related coupon payment. The securities will not be subject to automatic call until the first call date, which is
approximately six months after the issue date.
|
||
|
Call Dates*:
|
Quarterly, on the third business day prior to each coupon payment date scheduled to occur from April 2027 to January 2028.
|
||
|
Call Settlement Date:
|
Three business days after the applicable call date.
|
||
|
Maturity Payment
Amount (per security):
|
If the securities are not automatically called prior to the stated maturity date:
• if the ending price is greater than or equal to the downside threshold price, a cash payment equal to:
$1,000; or
• if the ending price is less than the downside threshold price, a number of shares of the Underlying Stock equal to:
the share delivery amount
|
||
|
Final Calculation
Day*:
|
April 25, 2028
|
||
|
Stated Maturity Date*:
|
April 28, 2028
|
||
|
Starting Price:
|
The stock closing price of the Underlying Stock on the pricing date
|
||
|
Ending Price:
|
The stock closing price of the Underlying Stock on the final calculation day
|
||
|
Downside Threshold
Price:
|
75% of the starting price
|
||
|
Share Delivery
Amount:
|
A number of shares of the Underlying Stock equal to the product of (i) the face amount divided by the
downside threshold price and (ii) the adjustment factor, rounded to four decimal places. The adjustment factor is initially set equal to 1.0 on the pricing date, subject to adjustment
|
||
|
Calculation Agent:
|
The Bank
|
Summary of Terms (continued)
|
Denominations:
|
$1,000 and any integral multiple of $1,000
|
|||
|
Agent Discount**:
|
Up to 2.075%; dealers, including Wells Fargo Advisors, LLC (“WFA”), may receive a selling concession of up to 1.50%, and WFA may receive a distribution
expense fee of 0.075%.
|
|||
|
CUSIP / ISIN:
|
89117HCT0 / US89117HCT05
|
|||
|
Material Canadian
and U.S. Tax
Consequences:
|
See the preliminary pricing supplement.
|
**In respect of certain securities, we may pay a fee of up to $2.00 per security to selected securities dealers for marketing and other services in connection with the
distribution of the securities to other securities dealers.
Hypothetical Payout Profile (maturity payment amount)
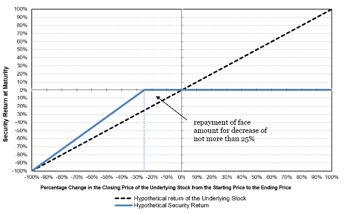
If the securities are not automatically called prior to stated maturity and the ending price is less than the downside threshold price, the value of the share
delivery amount that you will receive at maturity is expected to be worth less than the face amount of your securities and may be worthless. Additionally, the market value of the shares that you receive may be significantly lower than their market
value at the final calculation day because of any decrease in the market value of the Underlying Stock during the period between the final calculation day and the stated maturity date.
Any return on the securities will be limited to the sum of your coupon payments received. You will not participate in any appreciation of the Underlying Stock,
but , if the securities are not automatically called and the ending price is less than the downside threshold price, you will have downside exposure to the Underlying Stock on a leveraged basis from the starting price if the ending price as of the
final calculation day is less than the downside threshold price.
Our estimated value of the securities at the time the terms of your securities are set on the pricing date is expected to be between $935.00
and $970.00 per security. The estimated value is expected to be less than the public offering price of the securities. See “Estimated Value of the Securities” in the preliminary pricing supplement.
Preliminary pricing supplement:
|
* Subject to change.
|
|
This introductory term sheet does not provide all of the information that an investor should consider prior to
making an investment decision. The securities have complex features and investing in the securities involves a number of risks. See “Selected Risk Considerations” beginning on page P-10 of the preliminary pricing supplement,
“Risk Factors” beginning on page PS-5 of the product supplement MLN-WF-1 dated February 26, 2025 (the “product supplement”) and “Risk Factors” on page 1 of the prospectus dated February 26, 2025 (the “prospectus”). The securities are not
a bank deposit and not insured or guaranteed by the Canada Deposit Insurance Corporation, the U.S. Federal Deposit Insurance Corporation or any other governmental agency or instrumentality of Canada or the United States.
|
Selected Risk Considerations
The risks set forth below are discussed in detail in “Selected Risk Considerations” in the preliminary pricing supplement, “Risk Factors” in the product supplement and “Risk
Factors” in the prospectus. Please review those risk disclosures carefully.
Risks Relating To The Securities Generally
| • |
If The Securities Are Not Automatically Called Prior To Stated Maturity, You May Lose Some Or All Of The Face Amount Of Your Securities At Stated Maturity.
|
| • |
You May Be Exposed On a Leveraged Basis To The Decline In The Underlying Stock On The Final Calculation Day From The Starting Price, But Will Not Participate In Any Positive Performance Of The Underlying Stock.
|
| • |
Higher Coupon Rates Are Associated With Greater Risk.
|
| • |
You Will Be Subject To Reinvestment Risk.
|
| • |
Each Call Date and The Final Calculation Day, And The Related Call Settlement Date and The Stated Maturity Date, Is Subject To Market Disruption Events And Postponements.
|
Risks Relating To An Investment In The Bank’s Debt Securities, Including The Securities
| • |
Investors Are Subject To The Bank’s Credit Risk, And The Bank’s Credit Ratings And Credit Spreads May Adversely Affect The Market Value Of The Securities.
|
Risks Relating To The Estimated Value Of The Securities And Any Secondary Market
| • |
The Estimated Value Of Your Securities Is Expected To Be Less Than The Original Offering Price Of Your Securities.
|
| • |
The Estimated Value Of Your Securities Is Based On Our Internal Funding Rate.
|
| • |
The Estimated Value Of The Securities Is Based On Our Internal Pricing Models, Which May Prove To Be Inaccurate And May Be Different From The Pricing Models Of Other Financial Institutions.
|
| • |
The Estimated Value Of Your Securities Is Not A Prediction Of The Prices At Which You May Sell Your Securities In The Secondary Market, If Any, And Such Secondary Market Prices, If Any, Will Likely Be Less Than
The Original Offering Price Of Your Securities And May Be Less Than The Estimated Value Of Your Securities.
|
| • |
The Temporary Price At Which We May Initially Buy The Securities In The Secondary Market May Not Be Indicative Of Future Prices Of Your Securities.
|
| • |
The Agent Discount, Offering Expenses And Certain Hedging Costs Are Likely To Adversely Affect Secondary Market Prices.
|
| • |
There May Not Be An Active Trading Market For The Securities — Sales In The Secondary Market May Result In Significant Losses.
|
| • |
If The Price Of The Underlying Stock Changes, The Market Value Of Your Securities May Not Change In The Same Manner.
|
| • |
The Securities Will Be Subject To Single Stock Risk.
|
| • |
Any Payments On The Securities And Whether The Securities Are Automatically Called Will Depend Upon The Performance Of The Underlying Stock And Therefore The Securities Are Subject To The Following Risks, Each
As Discussed In More Detail In The Accompanying Product Supplement.
|
Risks Relating To The Underlying Stock
| • |
Investing In The Securities Is Not The Same As Investing In The Underlying Stock.
|
| • |
Historical Values Of A Market Measure Should Not Be Taken As An Indication Of The Future Performance Of Such Market Measure During The Term Of The Securities.
|
| • |
The Securities May Become Linked To The Common Stock Of A Company Other Than An Original Underlying Stock Issuer.
|
| • |
We, The Agents And Our Or Their Respective Affiliates Cannot Control Actions By An Underlying Stock Issuer.
|
| • |
We, The Agents And Our Or Their Respective Affiliates Have No Affiliation With Any Underlying Stock Issuer And Have Not Independently Verified Their Public Disclosure Of Information.
|
| • |
You Have Limited Anti-Dilution Protection.
|
Risks Relating To Hedging Activities And Conflicts Of Interest
| • |
Trading And Business Activities By The Bank Or Its Affiliates May Adversely Affect The Market Value Of, And Any Amount Payable On, The Securities.
|
| • |
There Are Potential Conflicts Of Interest Between You And The Calculation Agent.
|
Risks Relating To Canadian And U.S. Federal Income Taxation
| • |
The Tax Consequences Of An Investment In The Securities Are Unclear.
|
The Bank has filed a registration statement (including a prospectus) with the SEC for the offering to which this communication relates. Before you invest, you should read the
prospectus in that registration statement and other documents the Bank has filed with the SEC for more complete information about the Bank and this offering. You may get these documents for free by visiting EDGAR on the SEC website at www.sec.gov.
Alternatively, the Bank, any Underwriter or any dealer participating in the offering will arrange to send you the prospectus if you request it by calling your financial advisor or by calling Wells Fargo Securities, LLC at 866-346-7732.
Wells Fargo Advisors is a trade name used by Wells Fargo Clearing Services, LLC and Wells Fargo Advisors Financial Network, LLC, members SIPC, separate registered broker-dealers
and non-bank affiliates of Wells Fargo & Company.
2